Best States With No Income Tax for Retirees in 2026: Complete Relocation Guide

Choosing where to retire involves many factors, but tax considerations often play a decisive role in stretching your retirement savings.
Nine states currently collect no personal income tax on retirement income including Social Security, pensions, 401(k) withdrawals, and IRA distributions: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming.
For retirees with substantial retirement income, relocating to one of these states could save thousands of dollars annually.
The financial benefits extend beyond just income tax savings. You’ll need to weigh property taxes, sales taxes, and estate taxes against your specific financial situation. Some states with no income tax for retirees may have higher costs in other areas that offset the tax advantages.
Understanding how these states compare in terms of affordability, healthcare access, climate, and overall quality of life helps you make a decision that aligns with your retirement goals.
This guide examines the financial implications of each no-income-tax state, explores the trade-offs you might encounter, and provides practical steps for evaluating whether relocation makes sense for your situation.
Overview of Income Tax Policies in the United States
State income tax policies create significant financial differences for retirees across America, with nine states currently eliminating income tax entirely while others maintain varying rates that directly impact retirement income streams.
How State Income Taxes Affect Retirement
Your retirement income faces different tax treatment depending on where you live. Most states tax Social Security benefits, pension distributions, and withdrawals from retirement accounts like 401(k)s and IRAs as ordinary income.
State income tax rates range from zero to over 13% in some jurisdictions. This variation means your retirement savings stretch differently based on your chosen state. A $50,000 annual retirement income could face thousands of dollars in state taxes in high-tax states, while generating zero state tax liability in no-income-tax states.
You should consider that retirement income types receive different treatment. Some states exempt Social Security benefits even if they tax other income. Others provide special deductions for pension income or offer tax breaks specifically for seniors above certain age thresholds.
States With No Income Tax: Current List
Nine U.S. states impose no individual income tax on residents in 2026:
- Alaska
- Florida
- Nevada
- New Hampshire
- South Dakota
- Tennessee
- Texas
- Washington
- Wyoming
These states generate revenue through alternative methods. Sales taxes, property taxes, and other fees replace the income tax revenue stream. Texas and Washington rely heavily on sales taxes, while Alaska uses oil revenue to fund state operations.
New Hampshire previously taxed interest and dividend income but eliminated this tax, joining the other eight states with complete income tax elimination.
Recent Changes in State Tax Laws
Tennessee completed its transition to zero income tax by eliminating its tax on interest and dividends in recent years. New Hampshire followed a similar path, phasing out its interest and dividends tax.
Several states have adjusted their tax policies affecting retirees through expanded exemptions for retirement income. Some states now exclude larger portions of pension income or raised the income thresholds where Social Security benefits become taxable.
Property tax relief programs for seniors expanded in multiple states. These programs offer credits, freezes, or deferrals that help offset the higher property taxes often found in no-income-tax states.
Financial Advantages for Retirees in Tax-Free States
Living in a state without income tax can significantly increase your retirement budget by eliminating state-level taxation on earnings, withdrawals, and investment income. The savings extend beyond just income considerations to encompass property taxes, sales taxes, and how different retirement income sources are treated.
Impact on Retirement Income
When you retire in one of the nine states with no income tax, you keep more of your retirement distributions. Every dollar withdrawn from your 401(k), IRA, or other tax-deferred accounts remains free from state income taxation.
This advantage becomes substantial over time. If you withdraw $50,000 annually from retirement accounts, avoiding a 5% state income tax saves you $2,500 each year. Over a 20-year retirement, that equals $50,000 in preserved wealth.
Your investment income also benefits from this structure. Dividends, capital gains, and interest income remain untaxed at the state level. This allows your portfolio to generate returns without the drag of state taxation reducing your net income.
Social Security and Pension Considerations
38 states don’t tax Social Security benefits, but the states with no income tax provide automatic exemption. Your Social Security income remains completely untaxed at the state level, maximizing your monthly benefit.
Pension income receives the same treatment. Whether you receive payments from a government pension, private employer plan, or military retirement, you won’t pay state taxes on these distributions. This applies to both in-state and out-of-state pensions.
For retirees with substantial pension income, this creates meaningful savings. A $40,000 annual pension in a state with 6% income tax costs $2,400 yearly in taxes, while the same pension in a no-income-tax state remains fully yours.
Property Tax Implications
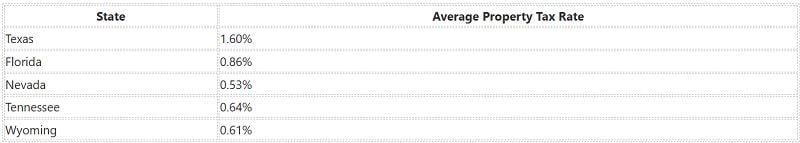
Property taxes vary significantly among no-income-tax states and can offset some savings. Texas has relatively high property taxes averaging 1.60% of home value, while Nevada averages 0.53%.
Average property tax rates in select no-income-tax states:
Some states offer additional property tax breaks for retirees. Florida provides homestead exemptions that can reduce taxable property value by up to $50,000. Alaska offers senior property tax exemptions for residents 65 and older.
You should calculate your total tax burden including property and sales taxes when evaluating relocation. A higher property tax rate might reduce the benefits of no income tax, depending on your home value and retirement income levels.
Cost of Living Differences Among Tax-Free States
Zero income tax doesn’t guarantee lower overall expenses. Housing markets, healthcare systems, and daily costs vary dramatically across the nine states without income tax, and these differences can overshadow any tax savings.
Housing Costs and Affordability
Housing represents the largest expense category for most retirees, and prices differ substantially among no-income-tax states. Florida’s median home price sits around $410,000, while Wyoming offers homes at roughly $310,000. Texas falls in the middle near $340,000, though major metros like Austin push well above this figure.
Property taxes complicate the affordability picture. Texas ranks among the highest nationally with an average effective rate of 1.74%, meaning a $350,000 home generates about $6,090 annually in property taxes. New Hampshire similarly burdens homeowners with elevated property tax rates. Florida maintains moderate property taxes around 0.89%, providing better balance for retirees on fixed incomes.
Rental markets show similar disparities. Washington state urban areas command $2,000+ monthly for modest apartments, while Tennessee offers rentals starting around $1,200 in many communities. Alaska’s remote location inflates both purchase prices and rental costs despite lower population density.
Healthcare Expenditures
Healthcare costs fluctuate significantly based on provider networks, insurance competition, and state regulations. Florida benefits from extensive Medicare Advantage plan options and competitive pricing due to its large retiree population. Average monthly premiums for supplemental coverage run $150-200 in Florida compared to $220-280 in Alaska.
South Dakota and Wyoming face challenges with limited healthcare infrastructure. Specialists remain scarce, and residents often travel long distances for advanced care. This geographic disadvantage increases both direct costs and time investments for medical appointments.
Texas provides mixed healthcare value. Major cities like Houston offer world-class medical facilities at competitive rates, while rural areas struggle with provider shortages. Tennessee similarly varies by region, with Nashville and Memphis providing robust healthcare networks.
Everyday Living Expenses
Sales taxes in no-income-tax states compensate for missing revenue streams. Tennessee charges 7% state sales tax, while Washington applies 6.5% plus local additions that push rates above 10% in Seattle. Florida’s 6% rate and Alaska’s absence of state sales tax offer more favorable shopping environments.
Utility costs respond to climate demands. Florida’s air conditioning needs generate summer electric bills exceeding $250 monthly. Wyoming’s heating requirements create similar winter expenses. Washington’s moderate climate reduces year-round utility demands.
Groceries and dining reflect both tax policies and regional economic conditions. A typical grocery basket costing $100 in South Dakota runs closer to $130 in Alaska due to shipping distances. Restaurant meals in Texas cities cost 15-20% less than comparable options in Washington’s metropolitan areas.
Insurance premiums beyond health coverage also matter. Florida’s hurricane risk elevates homeowners insurance to $3,000-6,000 annually, far exceeding Wyoming’s $1,200 average. Auto insurance follows similar patterns based on population density and weather risks.
Quality of Life Factors for Retirees
Beyond tax benefits, retirees in no-income-tax states need to evaluate climate conditions, availability of senior-focused services, and opportunities for staying active and engaged in their communities.
Climate Preferences
Your climate priorities depend on health conditions, lifestyle preferences, and tolerance for extreme weather. Florida, Nevada, and Texas offer warm winters that attract retirees seeking year-round sunshine and outdoor activities. These states rarely experience freezing temperatures, making them ideal if you want to avoid snow removal and icy conditions.
Washington and Alaska present the opposite climate profile. Washington’s Pacific Northwest location brings mild temperatures but significant rainfall, particularly in western regions. Alaska offers dramatic seasonal variations with long winter nights and limited sunlight, which can affect mood and vitamin D levels.
Tennessee combines moderate seasons with four distinct periods throughout the year. You’ll experience warm summers and cool winters without the extreme heat of desert states or the harsh cold of northern regions. This balance appeals to retirees who enjoy seasonal changes but prefer milder conditions.
Key Climate Considerations:
- Heat tolerance: Texas and Nevada regularly exceed 100°F in summer months
- Hurricane exposure: Florida and coastal Texas face seasonal storm risks
- Rainfall patterns: Washington averages 150+ rainy days annually
- Winter daylight: Alaska experiences as few as 4-5 hours of daylight in December
Access to Senior Services
Healthcare infrastructure varies significantly across no-income-tax states. Florida ranks among the best states for retirees due to its concentration of medical facilities, specialists, and senior care options. Major metropolitan areas like Miami, Tampa, and Jacksonville host nationally ranked hospitals and extensive networks of physicians trained in geriatric care.
Texas provides strong healthcare access in cities like Houston, Dallas, and Austin, which house major medical centers and research institutions. Rural areas of Texas may require longer travel times to reach specialized care facilities.
Nevada’s healthcare services concentrate heavily in Las Vegas and Reno. If you settle in rural Nevada counties, you’ll face limited options for routine care and may need to travel significant distances for specialist appointments.
Senior Service Availability by State:
- Assisted living facilities: Florida leads with over 3,000 licensed communities
- Medicare Advantage enrollment: Texas and Florida offer the most plan choices
- Home health agencies: Higher density in urban areas of all no-income-tax states
- Transportation services: Limited public transit in Wyoming, South Dakota, and Alaska
Recreational Opportunities
Your activity level and interests should align with what each state offers. Florida provides extensive golf courses, beaches, and water activities year-round. The state hosts numerous retirement communities with built-in recreational facilities, social clubs, and organized activities designed specifically for older adults.
Tennessee offers access to Great Smoky Mountains National Park, numerous lakes, and a rich musical heritage in Nashville and Memphis. You’ll find hiking trails, fishing spots, and cultural venues that support both active and leisurely pursuits.
Nevada and Texas cater to different recreational preferences. Nevada’s desert landscape suits hiking, off-road activities, and proximity to entertainment venues in Las Vegas. Texas provides diverse options from Gulf Coast beaches to Hill Country wineries and urban cultural districts.
Popular Retirement Activities by Region:
- Beach access: Florida (Atlantic and Gulf coasts), Texas (Gulf Coast)
- Mountain recreation: Tennessee, Alaska, Nevada, Wyoming
- Arts and culture: Major cities in Florida, Texas, Tennessee, Nevada
- Outdoor sports: Golf courses abundant in Florida, Texas, and Nevada
Comparison of Popular States With No Income Tax
Florida, Texas, and Tennessee stand out as the most popular destinations for retirees seeking to avoid state income taxes, each offering distinct advantages in climate, cost of living, and quality of life factors that extend beyond their tax structures.
Florida: Retirement Benefits and Drawbacks
Florida remains one of the nine states with no income tax in 2026, making it a prime destination for retirees looking to stretch their retirement dollars. The state does not tax Social Security benefits, pensions, or 401(k) withdrawals, which can save you thousands annually compared to high-tax states.
The state’s appeal extends beyond tax benefits. You’ll find no estate or inheritance taxes, and the property tax rate averages around 0.83% of assessed home value. Florida also offers a homestead exemption that can reduce your taxable property value by up to $50,000.
Key advantages include:
- Year-round warm weather and extensive coastline
- Large retiree communities with established healthcare networks
- No state income tax on any retirement income sources
However, you should consider some drawbacks. Property insurance costs have increased significantly, particularly in coastal areas prone to hurricanes. The state sales tax rate of 6% (with local additions bringing it to 7-8.5% in many areas) means you’ll pay more on everyday purchases. Summer heat and humidity can be intense, and hurricane season requires preparation and potential evacuation plans.
Texas: Economic and Lifestyle Considerations
Texas offers significant tax savings for retirees with no state income tax, but you need to understand the property tax trade-off. The state relies heavily on property taxes to fund services, with rates averaging 1.6% to 1.8% of home value, among the highest in the nation.
Your retirement income from all sources remains untaxed at the state level. This includes Social Security, pensions, IRA distributions, and investment income. For retirees with substantial retirement account withdrawals, this can offset higher property taxes.
The state’s low cost of living in many areas (outside major metro centers like Austin) helps your retirement savings go further. You’ll find diverse climates ranging from desert conditions in West Texas to humid subtropical weather along the Gulf Coast. The major cities offer world-class medical facilities, which becomes increasingly important as you age.
Sales tax rates range from 6.25% to 8.25% depending on local jurisdictions. Texas also has no estate tax, meaning your heirs won’t face state-level taxation on inherited assets.
Tennessee: Recent Trends and Insights
Tennessee completed its transition to a fully income-tax-free state after eliminating its Hall Tax on investment income in recent years. You won’t pay state taxes on wages, Social Security, pensions, or investment income as of 2026.
The state offers a moderate cost of living compared to coastal alternatives. Property taxes average around 0.64% of assessed value, well below the national average. Combined state and local sales taxes typically range from 8.5% to 9.75%, which you’ll need to factor into your budget for everyday expenses.
Tennessee’s four-season climate appeals to retirees who prefer distinct seasonal changes without harsh northern winters. The state has no estate or inheritance tax, protecting wealth transfers to your beneficiaries. Major cities like Nashville and Memphis provide cultural amenities and healthcare access, while smaller towns offer affordable housing and slower-paced living.
Your grocery purchases face a reduced sales tax rate of approximately 4%, lower than the general sales tax. This provides some relief on essential expenses compared to states that tax groceries at full rates.
Estate and Inheritance Tax Policies Across States
The federal estate tax exemption stands at $13.99 million in 2026, but individual states maintain their own estate and inheritance tax systems that can significantly impact your retirement wealth transfer. Georgia has no estate or inheritance tax, making it attractive for retirees concerned about legacy planning.
Legal Implications for Retirees
When you relocate to a state without income tax, you need to understand that estate and inheritance taxes vary considerably across jurisdictions. Some states impose estate taxes with exemption thresholds far lower than the federal level, potentially creating unexpected tax burdens for your beneficiaries.
States can levy both estate and inheritance taxes, and the distinction matters for your planning. Estate taxes are assessed on your total estate before distribution, while inheritance taxes are paid by your heirs based on what they receive and their relationship to you.
Your state of legal residence at death determines which state’s estate tax applies. If you maintain properties in multiple states, each state may claim a portion of your estate for taxation purposes based on the location of real property and other assets.
Planning for Heirs
Comprehensive planning across inheritance, estate, gift, and generation-skipping transfer taxes requires understanding your state’s specific rules. You should review exemption amounts and tax rates in your chosen retirement state to maximize what your heirs receive.
Strategic gifting during your lifetime can reduce your taxable estate in states with lower exemption thresholds. Some states allow spousal exemptions or reduced rates for direct descendants, which affects how you structure asset transfers.
Comparing state-by-state exemption thresholds and top rates helps you understand potential liabilities. Working with estate planning professionals familiar with your state’s laws ensures your wealth transfer strategies align with current regulations and protect your family’s financial interests.
Potential Drawbacks of Moving to a No-Income-Tax State
Moving to a state without income tax might seem attractive at first, but you need to understand the trade-offs. States require revenue to operate, and when they don’t collect income tax, they typically compensate through other means.
Higher Property and Sales Taxes
Several no-income-tax states have higher overall tax burdens than states with income taxes. Texas relies heavily on property taxes to fund government services, while Tennessee has some of the highest sales taxes in the country. You might save on income tax only to pay more when you buy goods or own property.
Increased Cost of Living
The cost of living in some no-income-tax states has soared in recent years. Housing costs, insurance premiums, and everyday expenses can offset any tax savings you gain. Florida, for example, has seen significant increases in property insurance costs.
Complex Residency Requirements
You’ll need to prove you’re a legitimate resident of your new state. This means establishing domicile, which involves more than just buying property. Residency rules can be complicated, and your former state may challenge your move if you maintain significant ties there.
Remote Work Tax Complications
If you work remotely for an employer in another state, you may still owe taxes to that state. This creates unexpected tax complications that can reduce or eliminate your anticipated savings.
Long-Term Trends and Projections for 2026 and Beyond
The landscape of no-income-tax states continues to evolve as demographic shifts reshape retirement destinations. States like Florida, Texas, and Nevada face increasing pressure on infrastructure and housing costs as retiree populations grow.
Key trends affecting no-income-tax states include:
- Rising property taxes to compensate for lack of income tax revenue
- Healthcare system strain in high-migration retirement areas
- Climate-related insurance cost increases in coastal states
- Growing competition among states to attract wealthy retirees
Wyoming has emerged as a top retirement destination due to its tax advantages and quality of life factors. The state combines zero personal income tax with relatively stable housing costs compared to traditional retirement havens.
Several states without income taxes are implementing new revenue strategies. You may see increased sales taxes, higher property tax assessments, or new fees for services that were previously subsidized. These changes can offset some of the tax savings you initially anticipated.
The difference between tax-friendly and tax-heavy states can exceed $15,000 annually on a $100,000 retirement income. This gap is projected to widen as high-tax states struggle with pension obligations and budget shortfalls.
Remote work normalization continues to influence where retirees choose to settle. You now have more flexibility to live near family while maintaining tax advantages, as adult children increasingly work remotely from lower-cost states. Climate considerations also play a larger role in long-term planning as extreme weather events become more frequent in certain no-income-tax states.
Key Steps for Making an Informed Relocation Decision
Before you pack your bags for a state with no income tax, you need to evaluate the complete financial picture. Moving from a high tax state to a low or no tax state requires deliberate actions and careful documentation to establish legal residency.
Start by calculating your total tax burden in your current state versus your potential new home. You should examine property taxes, sales taxes, and estate taxes alongside income tax rates. Some states without income tax compensate through higher property or sales taxes.
Critical factors to research include:
- Housing costs and property tax rates in your target area
- Healthcare availability and insurance premiums
- Sales tax rates on everyday purchases
- Estate and inheritance tax laws
- Proximity to family and friends
- Climate and lifestyle preferences
You need to understand residency requirements to avoid dual-state taxation issues. Most states require you to maintain a physical presence for a specific number of days and demonstrate intent to make the state your permanent home.
Visit your potential retirement destination multiple times throughout the year. You should experience different seasons and neighborhoods before committing to a move. Talk with current residents about their experiences with local services, healthcare facilities, and community activities.
Consult with a tax professional familiar with multi-state taxation rules. They can help you navigate the complexities of changing your domicile and ensure you meet all legal requirements for establishing residency in your new state.