How Much Do You Need Saved to Retire at 55? Essential Retirement Planning Guidelines

Retiring at 55 requires careful planning and a realistic assessment of your financial situation. Most financial experts suggest you’ll need between 10 to 15 times your annual expenses saved to retire comfortably at 55, though the exact amount depends on your lifestyle, location, and expected retirement length.
Early retirement usually requires a strong command of expenses and savings beyond what typical retirees need. The challenge with retiring at 55 goes beyond just accumulating enough savings.
You’ll need to cover healthcare costs before Medicare kicks in at 65, manage your investment withdrawals to last potentially 30 or more years, and account for inflation eroding your purchasing power over time.
Understanding the specific factors that influence your retirement number and how to calculate your personal target can mean the difference between a secure early retirement and running out of money.
This guide walks you through the critical calculations, investment strategies, and safeguards you need to retire at 55 with confidence.
Critical Factors Affecting Retirement Savings
Your retirement savings target depends on three interconnected variables: how long your money needs to last, what standard of living you expect to maintain, and how inflation will erode purchasing power over time.
Retirement Age Versus Life Expectancy
Retiring at 55 means your savings must support you for potentially 30 to 40 years. If you live to 85, that’s three decades without employment income. If you reach 95, you need four decades of financial support.
The gap between retirement age and life expectancy directly determines your withdrawal rate. A 55-year-old needs a lower annual withdrawal percentage than a 65-year-old with the same savings because the money must stretch across more years.
Life expectancy and healthcare costs both increase your required savings when retiring early. You’ll also need to bridge the gap until Social Security benefits begin, which you can claim as early as 62 but with reduced monthly payments. Waiting until full retirement age or 70 increases your benefit amount significantly.
Desired Lifestyle and Income Needs
Your annual expenses in retirement determine how much capital you need. If you plan to spend $80,000 per year, you need substantially more savings than someone planning to spend $40,000.
Estimating your retirement income needs requires examining your current spending and adjusting for retirement-specific changes. Some costs decrease, like commuting and work clothes. Others increase, particularly healthcare and leisure activities.
Many financial planners suggest replacing 70-80% of your pre-retirement income. However, this percentage varies based on whether you’ve paid off your mortgage, plan to travel extensively, or intend to relocate to an area with different living costs.
Inflation Impact Over Multiple Decades
Inflation reduces what your money can buy over time. At a 3% annual inflation rate, your purchasing power cuts in half roughly every 24 years.
What costs $50,000 today will cost approximately $81,000 in 20 years at 3% inflation. Over a 40-year retirement, that same $50,000 of annual expenses grows to $163,000 to maintain the same lifestyle.
Your savings strategy must account for this erosion. A portfolio generating 4% returns with 3% inflation only provides 1% real growth. This means you need either higher investment returns, larger initial savings, or acceptance of declining purchasing power in later retirement years.
Calculating Your Retirement Number
Determining how much you need to retire at 55 requires calculating your specific retirement number based on your expected expenses, planned withdrawal strategy, and Social Security timing. Your personal retirement target depends on maintaining your lifestyle while accounting for the decades of retirement ahead.
Estimating Annual Expenses in Retirement
You need to start by calculating what you’ll actually spend each year in retirement. Review your current monthly expenses and adjust for changes like eliminated commuting costs, paid-off mortgages, or increased healthcare spending.
Most financial planners suggest you’ll need 70-80% of your pre-retirement income to maintain your lifestyle. However, retiring at 55 means you’ll likely be more active in early retirement, potentially increasing travel and hobby expenses above this benchmark.
Create a detailed budget that includes:
- Housing costs (mortgage, taxes, insurance, maintenance)
- Healthcare and insurance (until Medicare at 65)
- Daily living expenses (food, utilities, transportation)
- Discretionary spending (travel, entertainment, hobbies)
- Unexpected costs (home repairs, medical emergencies)
Healthcare deserves special attention since you won’t qualify for Medicare for another 10 years. Private insurance or COBRA coverage can cost $700-$1,500 monthly per person.
Withdrawal Rate Strategies
The 25x rule suggests multiplying your annual expenses by 25 to determine your retirement number. If you need $60,000 annually, you’d need $1.5 million saved.
This calculation assumes a 4% annual withdrawal rate, which historically allows portfolios to last 30+ years. However, retiring at 55 means your money needs to last 35-40 years, making this strategy potentially aggressive.
Consider a more conservative 3-3.5% withdrawal rate for early retirement. Using a 3.5% rate, that same $60,000 annual need would require approximately $1.7 million saved. Retirement calculators can help you model different scenarios based on your specific situation and risk tolerance.
Your withdrawal strategy should also account for sequence of returns risk, the danger of market downturns early in retirement depleting your portfolio faster.
Social Security Eligibility and Timing
You cannot claim Social Security benefits until age 62, leaving a seven-year gap if you retire at 55. Your retirement savings must cover all expenses during this period without Social Security income.
Claiming at 62 permanently reduces your monthly benefit by approximately 30% compared to your full retirement age of 67. If your full retirement benefit would be $2,000 monthly, claiming at 62 reduces it to roughly $1,400.
Waiting until 70 increases benefits by 24% above your full retirement amount. This creates a strategic decision: use more retirement savings early while delaying Social Security, or claim reduced benefits sooner to preserve portfolio longevity.
Many early retirees use savings to bridge the gap until at least their full retirement age. This approach maximizes Social Security benefits while giving your portfolio more time to potentially recover from early withdrawals.
Investment Strategies for Early Retirees
Retiring at 55 requires a careful balance between growing your wealth and protecting it over a potentially 30-40 year retirement period. Your investment approach must account for longer time horizons, healthcare costs before Medicare eligibility, and the need to bridge income gaps until Social Security benefits begin.
Asset Allocation and Risk Tolerance
Your asset allocation at 55 should be more conservative than during your accumulation years, but not overly cautious given your extended retirement timeline. A common guideline suggests holding your age in bonds (55% bonds, 45% stocks), though many early retirees maintain 50-60% in equities to combat inflation over three or four decades.
You need to assess your risk tolerance based on your total wealth, guaranteed income sources, and flexibility to adjust spending. If you have a pension or rental income covering basic expenses, you can afford more stock exposure in your portfolio.
Key allocation considerations:
- Keep 1-3 years of expenses in cash or short-term bonds
- Maintain 3-5 years in intermediate-term bonds
- Allocate remaining assets to diversified stock holdings
- Rebalance annually to maintain target percentages
Your risk capacity differs from risk tolerance. Even if market volatility doesn’t bother you emotionally, you cannot afford significant losses in early retirement when sequence of returns risk is highest.
Building a Diversified Portfolio
Investing for growth remains important even after you stop working. Your portfolio should include domestic large-cap stocks, small-cap stocks, international equities, bonds of varying maturities, and potentially alternative investments like real estate investment trusts.
Index funds and exchange-traded funds offer low-cost diversification across asset classes. A simple three-fund portfolio, total U.S. stock market, total international stock market, and total bond market provides broad exposure with minimal effort and expenses below 0.10% annually.
Diversification elements:
- U.S. stocks: 30-40% across large, mid, and small caps
- International stocks: 10-20% in developed and emerging markets
- Bonds: 30-50% in government, corporate, and municipal bonds
- Real assets: 5-10% in REITs or commodities for inflation protection
You should avoid concentrated positions in individual stocks or your former employer’s stock. No single holding should represent more than 5% of your portfolio.
Tax-Efficient Withdrawal Planning
Your withdrawal strategy determines how long your savings last and how much you pay in taxes. You likely hold assets across taxable brokerage accounts, tax-deferred retirement accounts, and Roth accounts, each with different tax implications.
Before age 59½, you’ll need to access funds carefully to avoid early withdrawal penalties. You can withdraw Roth IRA contributions (not earnings) penalty-free at any age. You might also use substantially equal periodic payments (SEPP) or Rule 72(t) distributions from traditional IRAs.
The most tax-efficient approach typically involves drawing from taxable accounts first, allowing tax-advantaged accounts to continue growing. However, you should fill lower tax brackets with traditional IRA conversions to Roth accounts, especially before Social Security begins.
Withdrawal order strategy:
- Taxable account capital gains at 0% or 15% rates
- Tax-deferred account withdrawals to fill current tax bracket
- Roth conversions in low-income years
- Roth withdrawals when needed tax-free
You must also consider required minimum distributions starting at age 73, which can push you into higher tax brackets if you don’t plan ahead with strategic withdrawals and conversions in your 50s and 60s.
Bridging the Gap Before Medicare Eligibility
Retiring at 55 means you’ll need health coverage for a decade before Medicare begins at 65. Healthcare premiums for early retirees can be substantial, and choosing the right coverage strategy can save you tens of thousands of dollars during this transition period.
Health Insurance Options for Early Retirees
COBRA continuation coverage lets you keep your employer’s health plan for up to 18 months after retirement. You’ll pay the full premium plus a 2% administrative fee, which typically costs $600 to $700 monthly for individual coverage.
Marketplace plans through the Affordable Care Act provide another option. If your retirement income is low enough, you may qualify for premium tax credits that significantly reduce monthly costs. These plans are available year-round during special enrollment periods when you lose employer coverage.
Your spouse’s employer plan can cover you if they’re still working. Some employers also offer retiree health benefits, though these have become less common in recent years.
Health sharing ministries and short-term health plans offer lower premiums but provide less comprehensive coverage. Early retirement health insurance options vary based on the length of your coverage gap, with longer periods requiring more cost-efficient strategies than shorter transitions.
Managing Healthcare Costs Before 65
Healthcare premiums increase with age and can triple compared to rates for younger adults. Budget $800 to $1,500 monthly per person for marketplace coverage in your late 50s and early 60s.
High-deductible health plans paired with Health Savings Accounts let you save pre-tax dollars for medical expenses. You can contribute up to $4,300 individually or $8,550 for family coverage in 2026, with an additional $1,000 catch-up contribution if you’re 55 or older.
Building a dedicated healthcare fund within your retirement savings helps prevent gaps in coverage that could lead to high out-of-pocket costs. Plan for at least $100,000 to $150,000 in healthcare expenses between ages 55 and 65, including premiums, deductibles, and copays.
Adjustments and Safeguards for Longevity
Retiring at 55 means your portfolio needs to sustain you for potentially 30 to 40 years, requiring strategies to manage market downturns and ensure income doesn’t run out. Flexible spending approaches and guaranteed income products provide protection against outliving your savings.
Adjusting Spending for Market Volatility
Your withdrawal rate should flex based on market performance to preserve your portfolio during downturns. When markets drop significantly, reducing your spending by 10% to 20% can prevent you from depleting your assets during recovery periods.
The guardrails approach sets upper and lower spending limits tied to your portfolio value. If your account balance falls below a predetermined threshold, you cut discretionary expenses. When it rises above the upper guardrail, you can safely increase spending.
Key spending adjustments include:
- Skip annual inflation increases during bear markets
- Postpone major purchases when your portfolio declines 15% or more
- Increase withdrawals when markets perform exceptionally well
- Maintain essential expenses while cutting travel and entertainment first
You should review your withdrawal amount quarterly rather than setting it once annually. This allows faster response to market changes and reduces sequence-of-returns risk, which poses the greatest threat to early retirees.
Lifetime Income Products and Annuities
Annuities create a personal pension that covers essential expenses regardless of market conditions or how long you live. A portion of your retirement savings allocated to guaranteed income reduces the pressure on your investment portfolio.
Common annuity types for early retirees:
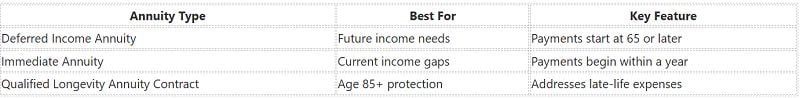
Allocating 25% to 30% of your portfolio to an annuity at 55 can cover fixed costs like housing, healthcare, and utilities. This creates a floor of guaranteed income that Social Security will supplement when you claim benefits. The remaining portfolio funds discretionary spending and inflation protection.
Common Pitfalls and Risk Management
Retiring at 55 requires careful planning to avoid expenses that exceed projections and market downturns that can deplete your savings during the critical early years of retirement.
Underestimating Expenses
Many people planning for early retirement fail to account for the full scope of their actual spending needs. Healthcare costs present one of the largest risks since you won’t qualify for Medicare until age 65, leaving a 10-year gap that requires private insurance or COBRA coverage.
You need to factor in inflation over a potentially 30-40 year retirement period. What costs $50,000 annually today will require approximately $90,000 in 20 years assuming a 3% inflation rate.
Common retirement savings mistakes include overlooking property taxes, home maintenance, and increased leisure spending. Track your current expenses for at least six months and add 10-20% as a buffer for unexpected costs.
Key expense categories to include:
- Healthcare premiums and out-of-pocket costs
- Home repairs and maintenance
- Property and income taxes
- Travel and entertainment
- Emergency fund replenishment
Sequence of Returns Risk
The order in which investment returns occur matters significantly when you’re withdrawing money from your portfolio. A market downturn in your first few years of retirement can permanently reduce your portfolio’s ability to recover, even if markets perform well later.
If you retire at 55 and experience a 20-30% market decline within the first five years, you’re forced to sell more shares to meet your income needs. This locks in losses and leaves fewer assets to benefit from eventual market recovery.
You can mitigate this risk by maintaining 2-3 years of expenses in cash or short-term bonds. This allows you to avoid selling stocks during market downturns and gives your portfolio time to recover before you need to liquidate assets.
Reevaluating and Updating Your Plan
Your retirement strategy requires regular reviews to stay aligned with your goals. Market fluctuations, lifestyle changes, and unexpected expenses can all impact whether you’re on track to retire at 55.
You should review your retirement plan at least annually. Schedule specific times each year to assess your progress and make necessary adjustments. This consistent approach helps you catch potential shortfalls early.
Key factors to monitor include:
- Investment performance and asset allocation
- Changes in living expenses or income
- Healthcare costs and insurance needs
- Tax law modifications
- Inflation rates
Major life events demand immediate plan updates. Marriage, divorce, inheritance, job changes, or health issues can significantly affect your retirement timeline and savings requirements.
You’ll want to track your withdrawal rate assumptions as you approach 55. What seemed realistic five years ago may need adjustment based on current market conditions. Using retirement calculators can help you verify whether your savings remain adequate.
Your risk tolerance should shift as retirement nears. Consider gradually moving toward more conservative investments to protect your accumulated wealth. However, you’ll still need some growth potential to sustain decades of retirement.
Don’t hesitate to consult a financial advisor when circumstances change significantly. Professional guidance becomes particularly valuable when you’re planning to retire early, as the longer retirement period requires careful planning. Regular updates ensure your plan remains realistic and achievable as you work toward your 55-year-old retirement goal.
Alternative Approaches and Supplemental Income
Generating additional income streams can significantly reduce the amount you need saved for retirement at 55, while part-time work and passive income sources provide both financial cushioning and personal fulfillment during your early retirement years.
Part-Time Work or Consulting
Transitioning to part-time work or consulting allows you to maintain income while enjoying greater flexibility. If you earn $30,000 annually through part-time work, you can reduce your portfolio withdrawals by that amount, potentially lowering your required nest egg by $750,000 based on the 4% rule.
Consulting in your former field often commands higher hourly rates than traditional employment. You can leverage decades of experience to work 10-20 hours per week, earning $50-$100 per hour depending on your expertise. This arrangement gives you control over your schedule while keeping you professionally engaged.
Early retirement strategies emphasize managing both expenses and supplemental income sources. Part-time work also helps bridge the gap until you can access Social Security benefits at 62 or reach full retirement age at 67.
Rental Income and Side Businesses
Rental properties generate passive income that doesn’t require active daily work. A single rental property producing $1,500 monthly provides $18,000 in annual income, reducing your portfolio dependency by approximately $450,000 in required savings.
Side businesses built before retirement can continue generating revenue with minimal time investment. Online businesses, creative ventures, or small-scale operations you’ve developed over time can produce $500-$2,000 monthly. These income streams offer tax advantages through business deductions while maintaining your retirement lifestyle.
Dividend-paying stocks and real estate investment trusts (REITs) provide additional passive income without property management responsibilities. A portfolio generating 3-4% in dividends creates steady cash flow while preserving your principal investment.