
The Business Behind Prediction Markets and Their Growing Digital Economy
Coatue Management led a $1 billion funding round for Kalshi on May 7, 2026, at a valuation of $22 billion. Five months earlier the company had been valued at $11 billion, and it told Bloomberg that annualized revenue had passed $1.5 billion. By early fall, Reuters was reporting advanced talks at $40 billion. We found no report that a round at that price had closed.
Those figures are the easy part. The harder question is what sort of company produces them. On the fee side, this looks like an exchange’s business, with a published formula and a federal regulator in Washington. On the customer side, it looks a lot like a sportsbook’s, and several court fights with states now turn on which description holds.
Kalshi’s revenue starts with one line of arithmetic
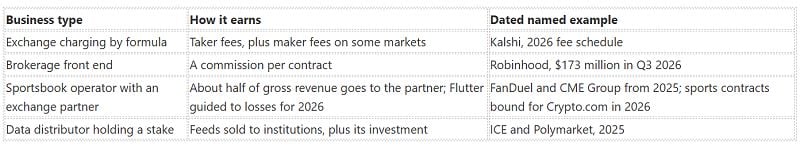
The fee schedule that took effect on July 7, 2026 multiplies 0.07 by the price, then by one minus the price, then by the contract count, and takers pay the result. One contract at 50 cents carries 1.75 cents before rounding. At 90 cents, the same line gives 0.63 cents. So the exchange earns the most per contract when a market looks like an even call, and much less once the outcome seems settled.
Scale does the rest. The company’s funding announcement put annualized trading volume at $178 billion, up from $52 billion six months before. Set the $1.5 billion revenue figure against that and the take comes to roughly 0.8 percent of volume. That’s our arithmetic, and it’s rough, because the two numbers came from separate statements.
Polymarket went the other way for years. On January 6, 2026, The Block described it as a platform that had “historically operated without charging users to trade,” in a story about new taker fees on its 15-minute crypto contracts. Its documentation now lists taker rates by category: 0.05 for sports, 0.04 for politics, zero for geopolitics. Makers pay nothing and get a share back as a rebate.
A formula can’t earn anything on its own, though. Somebody has to bring the traders.
Exchanges often leave the customer to someone else’s app
Plenty of those traders arrive through a product that belongs to another company, so one firm’s accounts tell only part of the story. Among the platform types listed under best prediction markets, two are channels more than venues. Brokerage and investing apps are one (Moomoo, the page says, plugs in Kalshi’s contracts without running an exchange of its own); sportsbook and fantasy operators that built their audience on betting first are the other.
The page’s description of each one shows what the distributor brings. For brokers, it names “one login, one funded account,” with the catch that the contract lineup may be narrower than on a dedicated platform. Operators bring the bet slip and the parlay screen their customers already use, and the page says they tend to run the heaviest promotions.
That arrangement splits one trade’s money between two companies. It splits the relationship too. The app owner handles the sign-up and the marketing, while the exchange runs the order book and collects its fee. An exchange that depends on a partner for customers has handed over a good deal of bargaining power, and the next two examples show how much.
Robinhood’s penny now outearns its crypto desk
Robinhood’s earnings release of October 27, 2026 reported $173 million in event contracts revenue for its third quarter, more than six times the figure a year earlier, on a record 16.4 billion contracts. Cryptocurrency revenue fell 55 percent to $120 million in the same quarter. Event contracts came to about 12 percent of total net revenue of $1.42 billion.
Its support page shows how small each slice is. The worked example there has a one-cent exchange fee and a one-cent Robinhood commission per contract. Divide the quarter’s revenue by its contracts and you get a little over a penny, which fits, though the company doesn’t break the number down that way and the example assumes a subscriber to its Gold tier.
The broker didn’t have to find a new audience for any of this. Our roundup of trading statistics counted 25.8 million funded Robinhood customers by mid-2025, people who had signed up for stocks and crypto and already had money in the account.
Then it moved up the chain. Rothera, its joint venture with Susquehanna International Group, passed $100 million in annualized revenue in its first full quarter, according to the same release, and has traded more than 6.4 billion contracts since launch.
Robinhood says it doesn’t wholly own or operationally control the venture. Even so, the support page now lists Rothera next to KalshiEX and ForecastEX as a venue for its contracts. A distributor that once rented an exchange now holds a stake in one, and we’d expect that to make the rented ones nervous.
CME went to FanDuel for the users
Terry Duffy didn’t dress it up. When CME Group and FanDuel unveiled FanDuel Predicts on November 12, 2025, the CME chairman said the launch “will dramatically expand our distribution and reach,” and tied that to FanDuel’s millions of registered US users. The Block’s report on the launch carried the same line. CME calls itself the world’s leading derivatives marketplace. Its chief was saying, in public, that retail reach would come from a sportsbook brand.
Neither company’s announcement gave a revenue split that day. Flutter, which owns FanDuel, supplied one in its first-quarter release this year: CME gets about 50 percent of FanDuel Predicts’ gross revenue before promotional spend. FanDuel carries the app’s costs, sales and marketing included, and CME carries the exchange’s.
The launch terms show whose interests shaped the product. Customers could trade the sports contracts in states without legal online sports betting, never on tribal lands, and FanDuel said it would stop offering them in any state that legalized. Flutter’s first-quarter release gave the company’s reasoning, describing prediction markets as “a very attractive, incremental opportunity providing an avenue to acquire customers ahead of sports betting regulation in new states.”
Here the economics stop resembling an exchange’s. The same release expected this year’s prediction-market losses to land toward the upper end of a guided $250 million to $300 million. This spring the company folded these users into the same FanDuel app its sportsbook customers use. Paying up front for customers and hoping they stay is how a betting company grows, and no exchange fee formula pays for it.
Then the partner with the customers changed the plumbing. Flutter’s second-quarter release said the two companies had agreed that all FanDuel Predicts sports and novelty contracts would move to Crypto.com, while customers kept access to CME’s financial markets. That came less than nine months after Duffy’s line about reach. The same release called FanDuel Predicts’ second-quarter revenue “not material.”
ICE bought a data feed before Polymarket charged a fee
Intercontinental Exchange, the company behind the NYSE, took a different seat. On October 7, 2025, it said it would invest up to $2 billion in cash in Polymarket, at a value of about $8 billion before the money went in, and become a worldwide distributor of the platform’s event-driven data to institutional investors.
Look at the timing. That announcement came three months before The Block reported those taker fees on 15-minute contracts, so ICE had no fee stream in view on that platform. Its own release talked about data.
The product arrived on February 11, 2026. ICE’s Polymarket Signals and Sentiment tool normalizes those prices, maps them to specific securities and companies, and reaches professional and institutional clients over the Consolidated Feed they already use. ICE said it would be “the exclusive provider of this data for institutional capital markets.” A retail trader pays to move a number, and a fund pays ICE to read it. ICE’s press release didn’t say what the tool earns.
Put the four arrangements in a row and one label can’t cover them.
State cases ask which of these businesses it is
Sports is where the two descriptions collide. Sporting Goods Intelligence put sports at 85 percent of Kalshi’s $112 billion lifetime volume in June 2026, and sports is the part states have gone after.
On December 2, 2025, Connecticut’s consumer protection regulator sent cease-and-desist notices alleging “unlicensed sports-related wagering” to Kalshi, Robinhood and Crypto.com. Two of the three names are companies the Bonus.com page files under brokerage apps, so the state’s letter reached past the exchange to the distribution.
Kalshi sued a day later, arguing that its markets are derivatives under federal oversight, and it lost the first round. In August 2026, U.S. District Judge Vernon Oliver denied its request for a preliminary injunction, writing that its sports contracts “fail to satisfy this portion of the statutory definition of a swap,” according to Bettors Insider’s account of the order. The wider lawsuit went on, and the Commodity Futures Trading Commission had a separate case against Connecticut pending at the time.
Massachusetts took the fight to state court. It sued Kalshi in 2025 and won a preliminary injunction early in 2026, and the Supreme Judicial Court fast-tracked the appeal, Insurance Journal reported. Reports since then disagree on whether the order has applied during that appeal, and we couldn’t settle it.
At argument that spring, Justice Scott Kafker told a company lawyer, “This does seem to have a major aspect of sports gambling to it.” The lawyer pointed to Dodd-Frank’s wider definition of a swap. We found no ruling as of late October. Questions from the bench don’t decide a case, and the outcomes so far have depended on the court and the state.
Anyone weighing these apps can read what they’ll actually be charged. A published fee schedule binds the exchange behind it, while Bonus.com on Facebook binds nobody to anything, which goes for social accounts generally.
What’s left to find out before a trade is mostly plumbing. Which company takes the commission, which one runs the book, and what happens to an open contract if a state orders the app to stop? The second answer can change, as FanDuel’s sports contracts showed this year. The fee comes off whether the contract finishes in the money or expires worthless, and on every contract one side does expire worthless.


